Risk Factors
The Group is committed to ERM*1 as the management platform for promoting its Mid-term Business Plan. Specifically, we will be constantly aware of the relationship between “risk,” “capital” and “profit,” and by realizing “capital adequacy” and “high profitability” in relation to risk, we will strive to achieve sustainable growth of corporate value.
-
*1Enterprise Risk Management
The risks surrounding the Tokio Marine Group are becoming more diversified and complex due to our global expansion and changes in the business environment. In today’s uncertain and rapidly changing political, economic, and social climate, we must proactively anticipate the emergence of new risks and their warning signs and take appropriate action. From this perspective, we are not limited to conventional risk management aimed at risk mitigation and avoidance, but are comprehensively assessing risks through both qualitative and quantitative approaches, including risks not previously recognized.
In addition, we are continuing our efforts to further strengthen the ERM framework. For instance, we are enhancing risk assessments to include risks that are difficult to quantify, such as cyber risks, and improving natural catastrophe risk management, including through reviews of our reinsurance schemes.
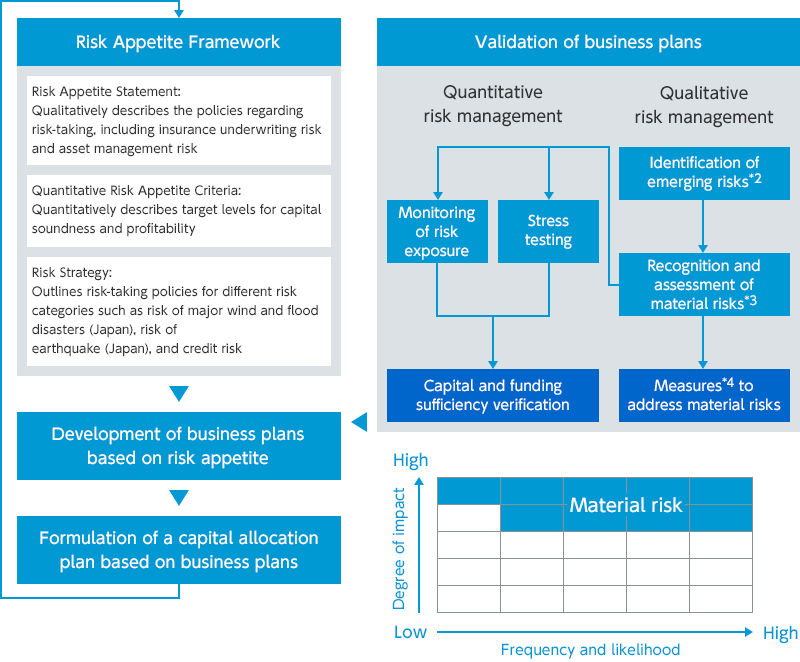
ERM Cycle
-
*2Emerging risks are new risks that arise due to changes in the environment or other factors, encompassing those that were not traditionally recognized as risks and those that have increased markedly in severity.
-
*3Material risks refer to risks that could have a substantial impact on financial soundness, business continuity, and other critical aspects. Specifically, we focus on emerging risks as well as material risks from the previous business year within the Group. We assess the impact (evaluating economic, business continuity, and reputational impacts) and consider the frequency and likelihood to identify the most significant factors. We specify these risks using the following 5×5 matrix.
-
*4For material risks, we formulate response measures (Plan), implement these measures (Do), assess the outcomes (Check), and make improvements (Act).
(1) Qualitative Risk Management
In qualitative risk management, all risks, including risks that emerge due to changes in the environment and risks not previously recognized, are identified and reported to management, while risks to the Group are discussed at the management level as needed.
Risks identified in this manner are evaluated not only in terms of the economic loss or frequency of occurrence but also in terms of business continuity and reputation. Risks that have a large impact on the financial soundness and business continuity of the Group or of individual Group companies are identified as “material risks.” For identified material risks, we assess the sufficiency of capital through the quantitative risk management process described in the subsequent pages, formulate control measures before the risks emerge and countermeasures*5 to be taken if the risks do emerge, and conduct PDCA management.
-
*5Pre-event risk controls include monitoring and aggregated risk management that consider market conditions and regulatory trends. Post-event measures include preparing manuals (including business continuity plans) and conducting emergency drills.
Detection of Emerging Risks and the Process of Identifying Material Risks

Examples of emerging risks
| Emerging risks | Examples of responses |
|---|---|
|
|
|
|
|
|
|
|
|
|
Material risks for fiscal 2025
| Material risks | Examples of responses |
|---|---|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
(2) Quantitative Risk Management
In quantitative risk management, the Company quantifies potential risks and conducts stress tests using risk models based on the latest knowledge available, verifying from multiple perspectives that its capital is sufficient relative to the risks it holds, with the aim of maintaining its credit ratings and preventing insolvency.
Specifically, the Company quantitatively evaluates risk using Value at Risk (VaR) at a 99.5% confidence level and verifies capital adequacy through the Economic Solvency Ratio (ESR), calculated by dividing net asset value*6 by risk amount. Our capital policy is determined comprehensively considering business investment opportunities and future market outlooks, among other aspects. Until the end of September 2025, capital adequacy was assessed using ESR based on a 99.95% VaR. However, following the implementation of Japan's Economic Value-Based Solvency Regulation at the end of March 2026, the ESR was redefined on a 99.5% VaR basis from the end of March 2026, to enhance comparability with global peers and alignment with the new solvency regulation. A 99.5% VaR refers to the level of loss that is not expected to be exceeded over a one-year period with a probability of 99.5%.
The Group aims to maintain an ESR of 190% or higher in order to preserve a capital level equivalent to an AA rating. As of the end of March 2026, the Group's ESR stood at 268%, confirming that its capital was at a sufficient level. In addition, on May 20, 2026, the Group announced its policy to conduct share repurchases of up to JPY 400 billion*7 throughout FY2026 in a flexible manner, after comprehensively considering market conditions, share price levels, and other relevant factors during the fiscal year. After reflecting the impact of these planned share repurchases, the ESR would be 255%.
For certain key risks namely, economic and financial crises, major earthquakes, and pandemics, we conduct stress tests on capital adequacy and liquidity based on scenarios assuming extremely severe economic losses, as well as scenarios in which multiple material risks occur simultaneously. Stress tests on liquidity are also conducted for major wind and flood disasters. In all cases, we have confirmed that no issues exist.
-
*6Calculated by adding the value of in-force life insurance business, deducting goodwill, and making other adjustments to consolidated net assets on a financial accounting basis.
-
*7Excluding the JPY 287.4 billion share repurchase announced on March 23, 2026 in connection with the strategic partnership with the Berkshire Hathaway Group. This share repurchase is intended to mitigate the dilution in value per share resulting from the increase in the number of shares outstanding following the third-party allotment of treasury shares to the Berkshire Hathaway Group. As the repurchase is accompanied by the disposal of treasury shares of an equivalent amount, its impact on the Group's capital level is limited and it has no impact on the ESR.
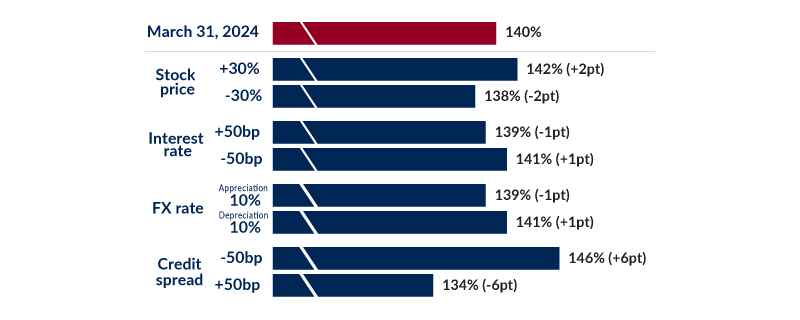
ESR Sensitivity